What Are Trade Credit Lines in Oil & Energy?

Bectran logo for blog posts

Bectran Product Team

I

September 24, 2026

4 minutes to read

Trade credit lines represent the credit extended by fuel distributors and petroleum marketers to their customers. Customers use trade credit lines to purchase products on terms rather than upfront. Grantors in the Oil & Energy sector maintain cash flow and mitigate risk by managing trade credit lines in a market defined by daily price fluctuations.

How do trade credit lines function for fuel distributors?

Trade credit lines in the Oil & Energy sector allow customers like trucking companies, construction firms, or other distributors to receive fuel or related products without immediate payment. B2B commerce relies on these credit lines. Customers manage their own working capital, and they receive a consistent supply. Unlike bank-issued credit, direct agreements between a supplier and a buyer reflect the supplier's assessment of the buyer's creditworthiness.

‍

A fuel distributor, when extending a trade credit line, evaluates a customer's ability to pay. Trade credit lines often involve high-value, high-volume transactions. The evaluation process typically begins with a credit application. The customer provides financial statements, trade references, and other relevant business information.

‍

The distributor then uses this data, along with credit bureau reports, to set a specific credit limit and payment terms, such as Net 10 EFT or Net 30. Credit limits and payment terms support sales. The grantor also protects itself from potential bad debt, a concern given the tight margins in fuel distribution.

What information is needed to establish a trade credit line?

Establishing a trade credit line requires a comprehensive review of a customer's financial health and operational history. Distributors often collect a packet of documents, including a formal credit application, personal guaranties, ACH authorization forms, W-9s, and sales tax exemption certificates. Credit extension relies on this legal and financial groundwork.

‍

Credit teams analyze this information alongside data from business credit bureaus like D&B, Creditsafe, or Ansonia Credit Data, which specializes in transportation. Some distributors also use internal criteria. For example, a trial credit limit of $5,000 for 6 to 12 months for new customers with limited credit history.

‍

The objective is to build a complete picture of the applicant's risk profile. A complete risk profile allows the grantor to make an informed decision on the appropriate credit limit and terms. The sales team often plays a role in gathering initial customer information. The credit department then reviews this information.

How are project-specific and high-volume trade credit lines managed?

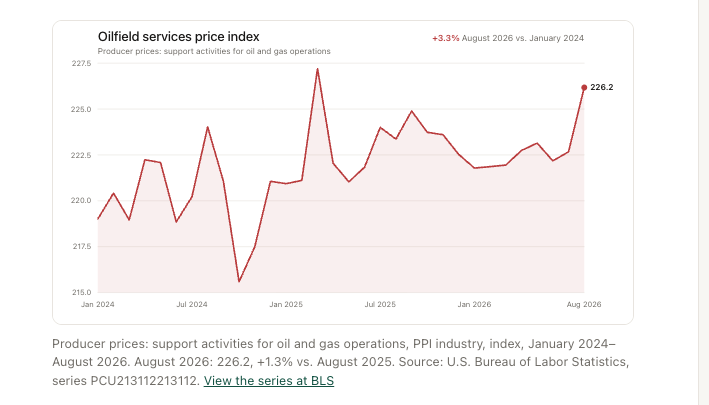
In sectors like construction or oilfield services, customers often require project-specific credit lines, sometimes referred to as "job sheets". A single customer might need hundreds or even thousands of these lines for different locations or projects. Manually processing each application can be a bottleneck. Manual processing consumes credit team resources.

‍

For established customers with a proven payment history, distributors streamline the creation of these numerous project lines. Distributors can use existing customer data from enterprise resource planning or customer relationship management systems to pre-fill applications. Distributors may even bypass the full application process for auto-approval based on predetermined criteria.

‍

Auto-approval shifts credit assessment from individual review to efficient, high-volume credit line provisioning. Bectran’s credit management platform can automate the creation and approval of multiple project-specific trade credit lines, such as job sheets, for established customers.

What impact does commodity volatility have on trade credit lines?

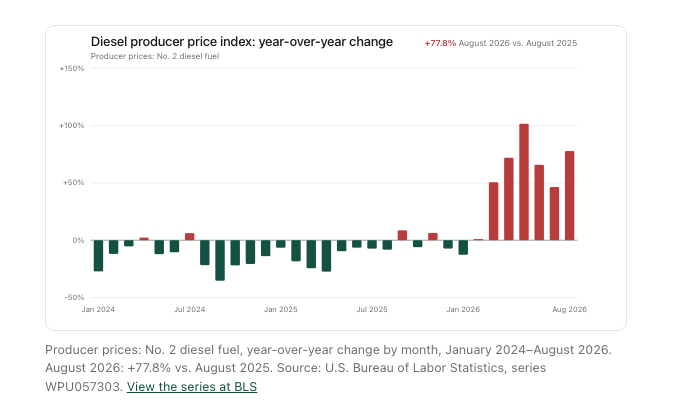
The Oil & Energy sector is susceptible to commodity price volatility. When rack prices for fuel increase, a credit limit set in dollars covers fewer gallons. The reduced gallon coverage effectively shrinks the customer's purchasing power. Distributor exposure per gallon delivered also increases. A credit limit established in January might represent a different business decision by July, even if the customer's payment behavior remains consistent.

‍

Distributors must continuously monitor market prices. They adjust credit limits or exposure calculations to reflect these changes. Failure to do so can lead to inflated accounts receivable books against static credit lines. Inflated accounts receivable books increase the risk of bad debt.

‍

Major oil traders secure billions in credit to brace for potential price spikes and margin calls. Securing billions in credit highlights the industry's sensitivity to market shifts.

How can trade credit lines be monitored and adjusted effectively?

Tracking payment behavior, reviewing aging reports, and reassessing credit limits constitute effective management of trade credit lines. Credit limit reassessments respond to changes in market conditions or customer financial health. For example, if a customer consistently makes partial payments or frequently exceeds their limit, it signals a need for review.

‍

Automated systems provide real-time alerts on credit exposure, payment trends, and expiring documents like tax exemption certificates. They can adjust terms, place accounts on credit hold, or require COD payments when necessary.

‍

The goal is to maintain a dynamic credit policy. This policy adapts to both customer performance and the volatility of the Oil & Energy market, protecting the grantor's financial interests.

Strengthen Your Trade Credit Decisions in a Dynamic Market

Bectran's credit management platform includes online credit applications with customer portals, automated credit scoring and decisioning, and multi-source bureau data aggregation. The system also provides workflows for credit hold and approval, and exposure-ratio monitoring. This is general information, not legal or tax advice. Walk through your own credit exposure with our team and identify opportunities to optimize your trade credit lines.

Frequently asked questions

What is a trade credit line?

A trade credit line is an agreement where a supplier extends credit to a customer. This allows them to purchase goods or services on deferred payment terms. It records the customer's payment history and is distinct from a bank loan, reflecting the supplier's direct assessment of creditworthiness.

How do trade credit lines differ from bank credit?

Trade credit lines are granted directly by suppliers for the purchase of their specific goods or services, like fuel. Bank credit is a financial product offered by banks, and it provides general access to funds that can be used for various business expenses. Trade credit lines focus on supplier-customer relationships.

Why are trade credit lines important in the Oil & Energy sector?

In the Oil & Energy sector, trade credit lines are important for facilitating the continuous supply of fuel and petroleum products. They allow customers to manage cash flow. They also enable distributors to secure sales. Effective management is important due to high transaction values and market price volatility.

How does Bectran help manage trade credit lines?

Bectran's platform streamlines the entire trade credit lifecycle. It provides online credit applications, automated decisioning, and multi-source bureau data aggregation. This helps credit teams make faster, more informed decisions and manage risk more effectively across their customer portfolio.

Can Bectran automate the approval of multiple project-specific trade credit lines?

Yes, Bectran can automate the creation and approval of multiple project-specific trade credit lines, such as job sheets, for established customers. Bectran integrates with ERP/CRM systems to pre-fill data. The platform also applies predetermined criteria for auto-approval, significantly reducing manual effort and accelerating onboarding.

September 24, 2026

Related Blogs